Losing a spouse can be a devastating and life-altering event, leaving many widows facing emotional and financial challenges. While no amount of money can replace the loss of a loved one, widow’s loans can be a valuable tool for navigating this difficult transition and providing much-needed financial stability.
With loans offered to widows, it becomes easier for them to handle financial emergencies with ease. There are various schemes available that are designed specifically for widows.

Types of Loan Schemes for Widows
Various government schemes are available for widows for their welfare & upliftment. Let’s go through each loan scheme from below:
Karnataka State Women’s Development Corporation – Udyogini Scheme
The Karnataka State Women’s Development Corporation’s (KSWDC) Udyogini Scheme is a fantastic initiative aimed at empowering women entrepreneurs in the state.
- Objective: To provide financial assistance and support to women entrepreneurs for setting up or expanding micro and small enterprises in various sectors.
- Loan Amount: Up to ₹3 lakhs for micro-enterprises and up to ₹10 lakhs for small enterprises.
- Interest Rate: Subsidized interest rates, currently hovering around 4% per annum.
- Repayment Tenure: Flexible repayment periods based on the loan amount and business type.
- Additional Support: The scheme also offers skill development training, business guidance, and marketing assistance to women entrepreneurs.
Eligibility:
- Women above 18 years of age residing in Karnataka.
- Belonging to any caste or community.
- Possessing entrepreneurial skills and a viable business plan.
Self-Employment Schemes for Ex-Servicemen (SEMFEX) and Widows
There are several Self-Employment Schemes for Ex-Servicemen (SEMFEX) and Widows in India that provide financial assistance and support for setting up or expanding small businesses. Here are some key details about the most notable schemes:
- Objective: To provide financial assistance to ex-servicemen, disabled service personnel, war widows, and widows of ex-servicemen for setting up micro and small enterprises in rural areas.
- Loan Amount: Up to ₹10 lakhs for agriculture and allied activities and up to ₹5 lakhs for non-farm activities.
- Interest Rate: Subsidized interest rates, currently around 4% per annum.
- Repayment Tenure: Up to 7 years for agriculture and allied activities and up to 5 years for non-farm activities.
- Additional Support: The scheme also offers skill development training and marketing assistance to beneficiaries.
Eligibility:
- Ex-servicemen with less than 20 years of service, or
- Disabled service personnel with 40% or more disability, or
- War widows and widows of ex-servicemen.
Pradhan Mantri Mudra Yojana (PMMY):
Pradhan Mantri Mudra Yojana (PMMY) is a government-backed scheme that provides micro-loans to small businesses. It was launched by the Government of India in April 2015 to promote entrepreneurship and economic growth. The scheme offers loans under three categories: Shishu Mudra, Kishore Mudra, and Tarun Mudra.
- Objective: To provide financial assistance to micro and small businesses across all sectors, including those run by ex-servicemen and widows.
- Loan Amount: Up to ₹10 lakhs categorized into Shishu Mudra (up to ₹50,000), Kishore Mudra (up to ₹5 lakhs), and Tarun Mudra (up to ₹10 lakhs).
- Interest Rate: Varies depending on the lender and loan amount
- Repayment Tenure: Up to 5 years.
Eligibility:
- Any aspiring entrepreneur, including ex-servicemen and widows, with a viable business plan.
- You must be a citizen of India.
- The minimum age is 18 years, and the maximum age is 65 years at loan maturity (may vary slightly between lenders).
- While not a strict requirement, a good credit score (usually 685 or above) improves your chances of approval.
Do widows need to have a job to qualify for a loan?
Not necessarily! Some widow loan programs in India, like PMMY or SEMFEX, focus on business viability, not employment, opening doors for entrepreneurship.
EMI Calculator for Widow Loan
The EMI Calculator for Widow Loan is a helpful tool that allows widows to estimate their Equated Monthly Installments (EMIs) based on factors like loan amount, interest rate, and repayment tenure.
By utilizing this calculator, widows can gain insights into the expected monthly repayment amounts, aiding in financial planning and ensuring that the loan remains within manageable limits.
Documents Required
The documents required for a widow’s loan change depending on the specific program, country/region, and loan provider (government, NGO, or private lender). Here are some general document categories likely to be requested by many widow’s loan programs:
- Proof of Identity: Passport, ID card, voter ID, driving license.
- Proof of Address: Utility bills, rental agreement, and property documents.
- Proof of Widowhood: Spouse’s death certificate, marriage certificate.
- Income Proof: Salary slips, bank statements, tax returns, and business license (if applicable).
- Age Proof: Birth certificate, passport, official documents.
- Additional Documents: Depending on the program, this could include property ownership documents, business plans, financial statements, guarantor details, etc.
Choosing the Right Loan for Your Situation as a Widow
There are multiple loan options a borrower can avail. As it can be both challenging and empowering at the same time. Finding the right fit depends on unique situations and intended goals. Here’s a guide to help make an informed decision:
- Government-backed schemes: Consider schemes like SEMFEX, Swavalamban, and PMMY with subsidized interest rates, relaxed eligibility criteria, and often skill development support.
- Traditional bank loans: Public and private banks offer personal loans with higher interest rates but potentially easier to access and may allow larger loan amounts.
- Microfinance institutions (MFIs): While interest rates are typically higher, MFIs cater to individuals with limited access to formal banking and offer smaller loans for income-generating activities.
Steps to Apply for a Widow’s Loan
Applying for a widow’s loan for financial support involves a series of simple steps designed for the borrowers in this case while securing the necessary funds during challenging times.
Follow the steps below to apply for a widow loan:
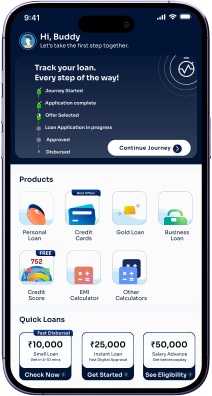
- Step 1: Visit buddyloan.com or download & install the Buddy Loan app (Android or iOS)
- Step 2: Open the personal loan application page. Provide the mobile number and enter the received OTP.
- Step 3: Specify the desired loan amount. Next, choose the Personal Loan option
- Step 4: Choose the employment type (salaried or self-employed) and the salary mode (bank or cash).
- Step 5: Enter your work details (including company name, years of service, and designation)
- Step 6: Enter your personal details (including full name, PAN, address, DOB & gender)
- Step 7: Provide your communication address and income details, and click the ‘Submit’ button.
Download the Buddy Loan App Now!
One solution to each of your financial needs at your fingertip.
Scan to download now