Personal loans for doctors act as a vital financial tool that helps medical professionals meet their unique financial needs. Loans for doctors provide flexibility and convenience to address various financial requirements, whether it’s a loan for doctors to set up a clinic or hospital, investing in advanced medical equipment, or even managing personal expenses.
To know more about loans for doctors in SBI, other banks, or any other government scheme for doctors, keep reading!

Instant Personal Loan for Doctors
Personal loans for doctors are tailored as crucial financial resources. These loans for doctors offer quick access to funds for various purposes. Buddy Loan offers interest rates for doctors starting at 9.99% p.a., while also providing convenience, speed, and minimal documentation. Now getting a professional loan for doctors is easier than ever!
The table below explores the general interest rates for doctor loans across different lenders:
| Interest Rates | 9% p.a. onwards |
| Loan Amount | ₹50000 to ₹50 Lakhs |
| Tenure | 1 to 5 years |
| Minimum Salary | 15,000/- |
| Approval | Working days of the bank |
Note: The interest rates are dynamic and subject to change based on your credit history and creditworthiness.
Interest Rates & Charges for Loans for Doctors
Securing the right loan for doctors, be it a personal loan or loan for business, having favorable terms is now more convenient than ever. It is important to understand the specifics of interest rates and associated charges to create a good financial future.
Check out the factors that influence a personal loan for doctors. These rates shed light on how doctors can optimize their financial decisions.
| Interest rate | 9.99% p.a. onwards |
| Processing fee | Up to 5% |
| Prepayment charges | Up to 2% |
| Pre-closure charges | 2% – 5% |
| Late payment charges | 1% – 3% |
| Stamp duty | 4% and 6% |
| Cheque bounce charges | ₹200 – ₹500 |
Note: The interest rates are dynamic and subject to change based on your credit history and creditworthiness.
Eligibility Criteria for Loans
Loans for doctors come with personalized eligibility criteria to meet several financial needs of medical professionals. Getting a personal loan for doctors includes checking these basic criteria, which would include minimum income requirements and age restrictions and so on. The table below gives a guide to a doctor loan eligibility criteria
| Citizenship | Indian |
| Age of the borrower | 21 – 60 years old |
| Credit score | 600 above |
| Employment | Self-employed |
| Minimum monthly income | ₹15,000 |
Note: The interest rates are dynamic and subject to change based on your credit history and creditworthiness.
Documents Required for Loan
When getting a professional loan for doctors, knowing the required documentation is necessary for a successful loan availing process.
This list below provides all details of essential documents needed for your doctor’s loan application. Furthermore, we explain the significance of each document. It helps doctors understand why these documents are crucial in securing a personal loan for financial support they require.
- Identity Proof: This helps to identify the borrower’s identity and citizenship.
- Aadhaar card, passport, voter ID, or PAN card.
- Address Proof: To confirm the borrower’s residential address.
- Utility bills, passport, Aadhaar card, or rental agreement.
- Income Proof: To assess the applicant’s income stability and repayment capacity.
- Business income tax returns, profit and loss statements, balance sheets, or audited financials.
- Bank Statements: To verify the applicant’s financial transactions, income, and expenditures.
- Bank statements for the last 6 to 12 months.
- Business Proof: To confirm the existence and legality of the applicant’s business.
- Business registration documents, GST registration, business PAN card, or shop and establishment certificate.
- Tax Returns: To assess the applicant’s tax compliance and income history.
- IT returns for the last 2 to 3 years.
EMI Calculation & Repayment
Understanding EMI calculations for a personal loan for doctors is essential. EMI offers a clear, unique explanation of how much money you would need to pay for your loan amount. The EMI tool will help you move your financial decisions in the right direction.
Your Amortization Schedule (Yearly/Monthly)
To calculate the EMI for a loan for doctors manually, you can use the formula:
| EMI = P x R x [(1+R)^N] / [((1+R)^N) – 1] |
Where,
- EMI is the equated monthly installment.
- P is the principal amount.
- R is the interest rate.
- N is the loan tenure.
For a more personalized EMI calculation for personal loans for doctors, explore our EMI calculator tool linked. By providing simple details like the interest rate, tenure, and your loan amount, you can know your EMI:
Note: The interest rates mentioned are subject to change. Do visit the website for more information.
Types of Loans Offered to Doctors
For medical professionals, financial needs come in unexpected ways & times. Here’s a simplified guide on loan types.
- Personal loans: Personal loans are unsecured loans that can be used for any purpose. They are typically easier to qualify for than other types of loans, such as business loans, and they offer flexible repayment options.
- Business loans: Business loans are specifically designed to help businesses finance their operations. They can be used for a variety of purposes, such as working capital, equipment purchase, and inventory financing. You can avail a business loan by submitting collateral, such as business assets or personal assets.
- Healthcare equipment loans: Healthcare equipment loans are specifically designed to help doctors finance the purchase of medical equipment &/or other inventories, such as X-ray machines, ultrasound scanners, and surgical tables.
- Loans against property: Loans against property are secured loans that allow borrowers to borrow money against the value of their property. These loans can be used for a variety of purposes, such as consolidating debt, financing a major purchase, or meeting unexpected expenses.
- Home loans: Home loans are secured loans that are used to purchase a home. They typically have lower interest rates than personal loans, but they also require a down payment.
Features & Benefits of Loans For Doctors
Personal loans for doctors offer financial flexibility to medical professionals, helping them manage personal expenses and unexpected financial requirements. Eligible doctors can also explore specialized professional loans for clinic expansion and equipment purchases.
Here are the key features and benefits:
- Collateral-Free Loans: Access unsecured personal loans without pledging property or other assets.
- Higher Loan Amounts: Eligible doctors can borrow up to ₹50 lakh through select personal loan products.
- Competitive Interest Rates: Lenders may offer favorable rates based on income stability, credit score, and professional experience.
- Flexible Repayment Tenure: Choose repayment periods of up to 72 months with select lenders.
- Quick Loan Processing: Digital applications and document verification help simplify the borrowing process.
- Minimal Documentation: Apply using KYC documents, bank statements, income tax returns, and relevant professional records.
- Multiple Loan Purposes: Cover medical emergencies, education, home renovations, and other permitted personal expenses.
- Specialized Professional Financing: Explore dedicated business loans for clinic expansion, equipment purchases, and working capital.
Loan eligibility and benefits vary by lender.
Note: The interest rates are dynamic and subject to change based on your credit history and creditworthiness.
Loan for Doctors With Buddy Loan
Experience a hassle-free journey to financial empowerment with Buddy Loan, where we simplify the application process for specialized doctor loans.
Steps to apply for a personal loan with Buddy Loan:
- Step 1: Visit buddyloan.com or download & install the Buddy Loan app (Android or iOS)
- Step 2: Open the personal loan application page. Provide the mobile number and enter the received OTP.
- Step 3: Specify the desired loan amount. Next, choose the Personal Loan option
- Step 4: Choose the employment type (salaried or self-employed) and the salary mode (bank or cash).
- Step 5: Enter your work details (including company name, years of service and designation)
- Step 6: Enter your personal details (including full name, PAN, address, DOB & gender)
- Step 7: Provide your communication address and income details, and click the ‘Submit’ button.
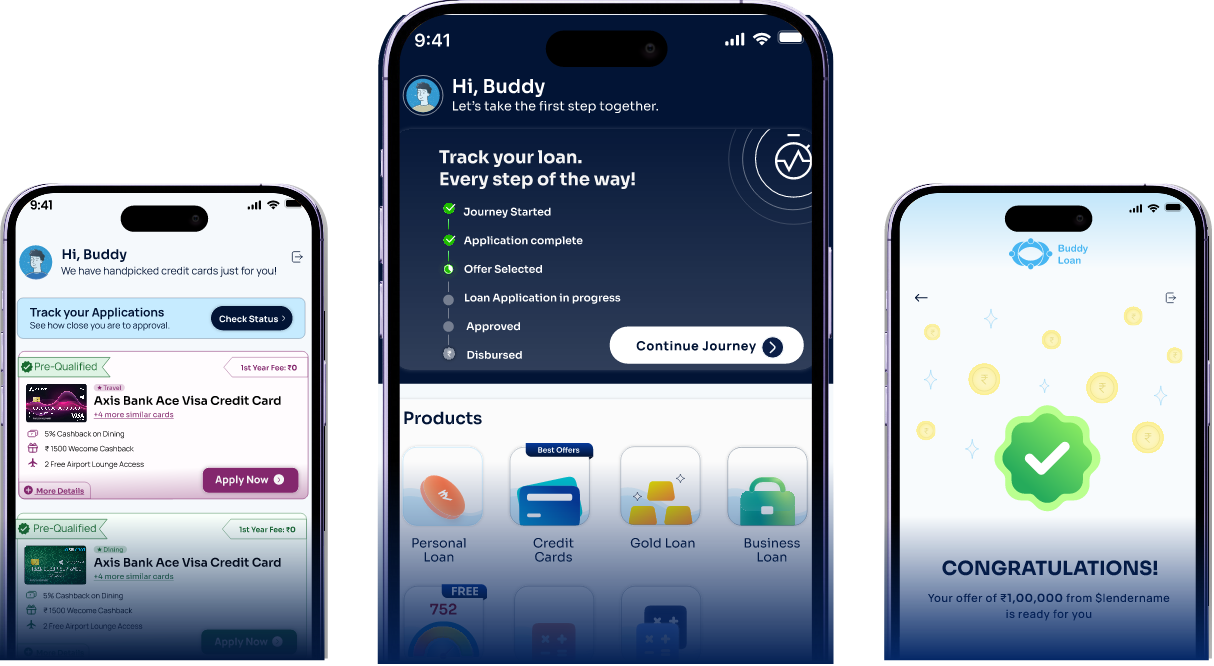
Download the Buddy Loan App Now!
One solution to each of your financial needs at your fingertip.
Scan to download now