

Make your education dreams a reality with education loans from 30+ banks and NBFCs. Compare interest rates, explore flexible repayment options, and choose a loan that fits your needs. Take the next step toward your future with confidence.
Top Banks Providing Education Loans in India
Explore education loan options from leading banks in India. Compare interest rates and loan terms to find a suitable option that fits your needs, including instant education loan options.
| S.No | Lenders | Interest Rates | Processing Fee | Max Loan Amount |
| 1. | HDFC Bank | 9.55% onwards | Up to 1.50% | Up to ₹1.5 Crore |
| 2. | ICICI Bank | 8.50% onwards | Up to 2.00% | Up to ₹3 Crore |
| 3. | IndusInd Bank | 10.50% onwards | Up to 2.00% | Up to ₹1.5 Crore |
| 6. | Central Bank of India | 8.05% onwards | Up to 1.00% | Up to ₹2 Crore |
| 7. | Bandhan Bank | 9.95% onwards | Up to 1.00% | Up to ₹50 Lakh |
| 8. | State Bank of India | 8.15% onwards | Up to ₹10,000 | Up to ₹3 Crore |
*Note: Final interest rates, loan amounts, and processing fees depend on the co-applicant’s credit score, the university category (premier or non-premier), the course type, and whether collateral is required. An additional 18% GST applies to the processing fees listed above.
Top Indian NBFCs Providing Student Loans
Explore education loan options from leading NBFCs in India. Compare interest rates, loan amounts, and repayment terms to find a student loan that suits your financial needs.
| S.No | Lenders | Interest Rates (p.a.) | Processing Fee | Max Loan Amount |
| 1. | Aditya Birla Capital | 10.9% onwards | Up to 2.50% | Up to ₹50 Lakh |
| 2. | Tata Capital | 9.5% onwards | Up to 2.00% | Up to ₹2 Crore |
| 3. | Money View | 14% onwards | Up to 8.00% | Up to ₹10 Lakh |
| 4. | IIFL | 11.88% onwards | Up to 3.00% | Up to ₹50 Lakh |
| 5. | Bajaj Finserv | 10% onwards | Up to 4.00% | Up to ₹1 Crore |
*Note: Final interest rates, loan amounts, and processing fees depend on the co-applicant’s credit score, the university category (premier or non-premier), the course type, and whether collateral is provided. An additional 18% GST applies to the processing fees listed above.
Education Loan Interest Rates
Education loan interest rates affect the total cost of your higher education. In India, these rates typically range from 9% to 12% per annum. Compare offers from different lenders to find a suitable rate and repayment plan. Understanding the factors that affect interest rates can help you choose an affordable education loan and plan your finances better.
Factors Affecting Interest Rates
- Credit Score: Credit score and credit history can affect your interest rate. A higher credit score may help you get a lower rate, while a lower score may lead to a higher rate.
- Loan Tenure: The repayment period can affect your loan terms. Longer tenures may come with different interest rates, depending on the lender.
- Loan Type: Subsidised and unsubsidised education loans may have different interest rates. Subsidised loans generally offer lower rates. Some students may also consider a personal loan to fund higher education.
- Market Conditions: Economic trends and changes in market interest rates can affect education loan rates. Government education loan schemes may have different rates and terms.
- Lender Policies: Each lender sets rates based on its policies, funding costs, operating expenses, and loan scheme. Compare offers from different lenders to find an option that suits your needs.
Education Loan EMI Calculator
The education loan EMI calculator helps students estimate their monthly loan payments.
Use the student loan calculator to check your EMI, understand the total repayment cost, and plan your budget before applying for an education loan. This helps you assess affordability and make informed financial decisions.
Education Loan Eligibility Criteria
Education loan eligibility depends on factors such as age, nationality, academic qualifications, credit history, income, and co-applicant or guarantor requirements. Use an education loan eligibility calculator to check whether you meet the basic requirements before applying.
The table below will show the education loan eligibility in India:
| Eligibility Criteria | Description |
| Nationality | Indian |
| Age | 18 years to 35 years |
| Academic record | Proven to be Good |
| Qualification | Must be pursuing a graduate/postgraduate degree or a PG diploma. |
| Income source | Parents/guardians must have a stable income. |
| University Applied | Recognised University in India or Abroad |
| Admission Status | Confirmed admission to the university |
| Security | Based on the loan amount and income source, tangible collateral or a guarantor may be required. |
Documents Required to Apply for Education Loan
To complete your education loan application, you must submit the necessary education loan documents. Refer to the following list of documents required for an education loan to ensure you have all the required paperwork.
- Filled & signed application form with affixed photographs
- Two photographs
- Mark sheets of 10th/12th or latest education certificate
- Statement of the cost of the course
Age proof:
- Aadhaar Card
- Voter ID
- Passport
- Driving Licence
Identity proof:
- Voter ID
- Aadhaar Card
- Driving Licence
- Passport
Residence proof:
- Rental agreement
- Bank statement of 6 months of the student or co-borrower/ guarantor
- Gas Book / Electricity Bill / Tel Bill
Income proof:
- Salary slips/Form 16 of the parent/ guardian/co-borrower
- Bank statement (last 6 months) of the borrower
- ITR of two years of parent/co-borrower/guardian
Education Loan Fees and Charges
When enquiring about the application for the fee structure for an education loan, it’s crucial to consider the associated costs and other charges. Compare the processing fees for education loans offered by different lenders to make an informed decision.
| Loan Details | Charges |
| Processing Fee | A fee of 1% to 2% will be charged based on the loan amount. |
| Foreclosure/Prepayment Charges | Typically ranges from 0% to 5% of the outstanding loan amount. |
| EMI Bounce Charges | Typically ranges from Rs. 200 to Rs. 500 per instance. |
| Overdue Charges on EMI | Generally ranges from 1% to 3% per month on the overdue installment amount. |
| Legal Fee | Ranges from 0.1% to 1% of the loan amount. |
Instant Education Loan Without Collateral
Instant loan options for education without collateral can help students access funds based on their creditworthiness and academic performance, without pledging any assets as security.
These loans remove the need for collateral, making it easier for students to fund their education and work toward their academic goals.
Pre-approved Education Loan
A pre-approved education loan is offered based on a student’s creditworthiness and academic qualifications. The lender reviews the student’s profile and sets a loan amount and terms in advance, which may simplify the application process.
Pre-approval can help students access funds more quickly and reduce the steps involved in getting a loan. This allows them to focus on their studies while planning their education expenses.
Improve Chances of Getting an Education Loan
The table below lists the do’s and don’ts to improve your chances of getting an education loan in India. It also explains how your parents’ credit score can affect your loan eligibility.
| Do’s | Don’ts |
| Maintain a good credit score | Default on previous loan repayments |
| Research and compare different lenders | Submit incomplete or inaccurate application documents |
| Consider parents’ credit score as it affects student loans | Underestimate the impact of parents’ credit history on loan eligibility |
| Demonstrate a clear academic and career plan | Provide false information about your educational background |
| Have a well-defined repayment strategy | Apply for an excessive loan amount |
| Provide all necessary supporting documents | Hide any existing financial obligations |
| Seek a co-applicant or guarantor, if required | Apply with multiple lenders simultaneously |
Education Loan for Abroad Studies
Education loans for studying abroad can help students pursue international education without pledging collateral, subject to the lender’s eligibility criteria. Interest rates typically range from 8% to 15% per annum, depending on the lender and the borrower’s profile. Compare interest rates, loan terms, and other charges to find a suitable loan for your overseas education.
These loans can help cover the cost of studying at universities around the world. They may also offer flexible funding for tuition, living expenses, and other education-related costs, making international education more accessible to students from different backgrounds.
Types of Education Loans in India
Education loans are mainly divided into two types based on where you plan to study: in India or abroad. The table below explains both options.
Location-Based Education Loans
Education loans can also be classified by the type of course you plan to pursue. The table below lists the different types of education loans based on the course.
| Loan Type | Description |
| Domestic Education Loan | These loans are designed for students pursuing education within India, covering expenses like tuition. fees, books, and living expenses for undergraduate, postgraduate, and professional courses. |
| Study Abroad Education Loan | This loan covers tuition fees, living expenses, travel costs, etc., for students pursuing education. abroad, including undergraduate, postgraduate, doctoral, and vocational courses. |
Courses-Based Education Loans
Education loans can also be grouped by the type of course you plan to pursue. The table below explains the different types of education loans based on the course.
| Loan Type | Description |
| Graduate Education Loans | These loans are designed for postgraduate or master’s degree students, covering expenses like tuition. fees, accommodation, study materials, and related costs. |
| Undergraduate Education Loans | These loans fund bachelor’s degree education in arts, science, commerce, engineering, medicine, etc. They cover tuition fees, accommodation, books, equipment, and expenses incurred during the undergraduate course. |
| Location-based Education Loans | This loan is tailored to students studying in specific regions, offering benefits, interest rates, and financial support based on location. Terms and conditions vary by region. |
List of Expenses Covered in Education Loan
The following is a comprehensive list of expenses typically covered by an education loan in India.
- Tuition fees: Covers the fees charged by the educational institution for your course.
- Accommodation expenses: These include the cost of staying in a hostel or renting accommodation during the course of study.
- Books/ study materials: The loan covers expenses related to textbooks, reference books, study guides, and other required study materials.
- Examination fees: These include fees for exams, assessments, and other evaluation processes during the course.
- Equipment and supplies: The loan may cover the cost of purchasing or renting necessary equipment, such as laptops, scientific instruments, or tools, required for the educational program.
- Insurance: Some education loans include insurance coverage for the student, offering financial protection in case of unforeseen events or emergencies.
Tax Benefits of Education Loan
Education loans help students fund their studies and may also offer tax benefits. The education loan tax exemption can help reduce the financial burden on students and their families. Here are the key tax benefits available on education loans in India:
- Section 80E Deduction: You can claim a tax deduction on the interest paid on an education loan under Section 80E of the Income Tax Act.
- Duration of Deduction: You can claim the deduction for up to 8 consecutive years or until you repay the interest in full, whichever comes first.
- Interest deduction Only: The tax deduction applies only to the interest paid on the education loan, not the principal amount.
- No Cap on Courses or Streams: The tax benefit is available for all courses and streams of study, including both professional and non-professional courses.
- Documentation Requirement: Maintaining proper documentation of the education loan and interest payments is important to claim the tax deduction accurately.
- No Maximum Limit: Unlike many other tax deductions, there is no upper limit on the amount that can be claimed as a deduction for education loan interest.
Steps to Apply for a Education Loan
Here are the steps you can follow to apply for an education loan on Buddy Loan, outlining the education loan process:
- Step 1: Visit buddyloan.com or Download & install the Buddy Loan app (Android or iOS).
- Step 2: Open the Personal Loan Application Page. Provide the mobile number and enter the received OTP.
- Step 3: Specify the desired loan amount & personal email. Next, choose the Personal Loan option
- Step 4: Choose the employment type (Salaried, Self-Employed, or Student) and the salary mode (bank or cash).
- Step 5: Enter your work details (Including company name, years of service and Designation)
- Step 6: Enter your personal details (Including Full Name, PAN, address DOB & Gender)
- Step 7: Provide your communication address, and income details and Click the ‘Submit’ button.
Education Loan Repayment
Education loan repayment involves paying back the borrowed amount along with interest. You can repay through regular monthly instalments (EMIs), full prepayment, or part-payment.
Full prepayment means repaying the entire outstanding loan before the end of the tenure. It can help you close the loan early and save on interest.
Part-payment means paying a lump sum towards your outstanding loan balance. This reduces the principal amount and may lower the total interest you pay over time.
Borrowers have access to different methods of loan repayment, which include:
- Electronic Clearing Service (ECS): Automatic deduction of monthly installments from the borrower’s bank account.
- Post-Dated Checks (PDCs): Providing post-dated checks to the lender for monthly repayments.
- Online Fund Transfer: Initiating online transfers from the borrower’s bank account to the lender’s account.
- Mobile Banking: Utilizing mobile banking applications to make loan repayments.
- NEFT/RTGS: Transferring funds electronically using National Electronic Funds Transfer (NEFT) or Real-Time Gross Settlement (RTGS) systems.
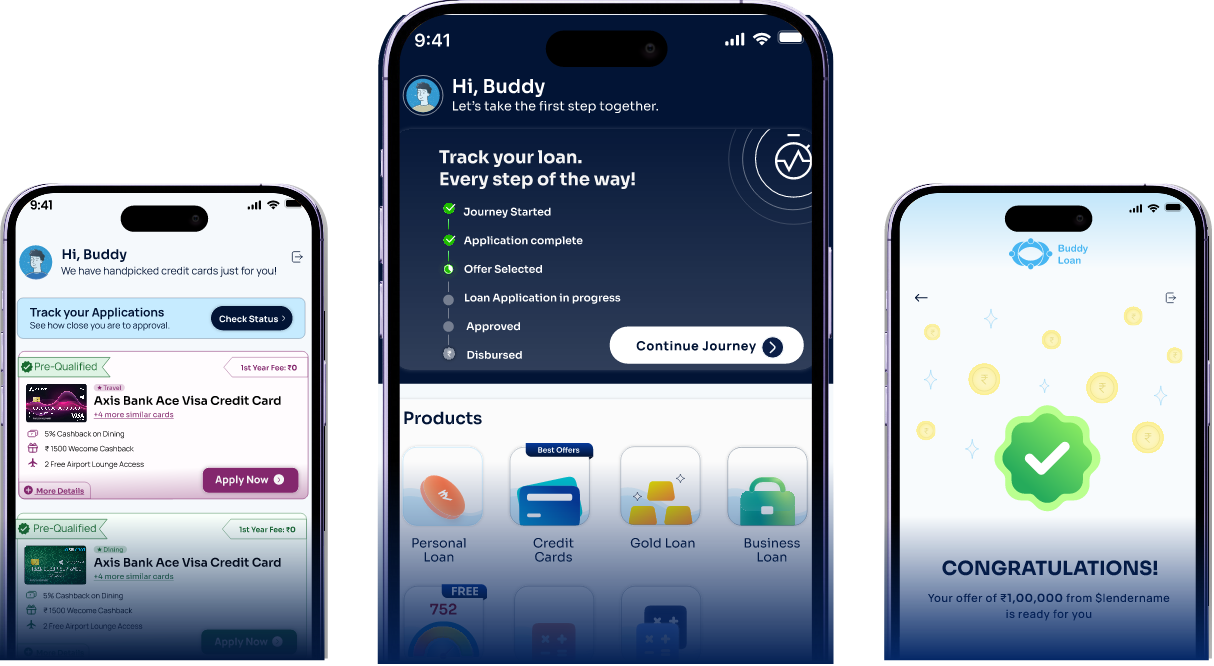
Download the Buddy Loan App Now!
One solution to each of your financial needs at your fingertip.
Scan to download now