J&K Bank offers personal consumption loans for employees, professionals, pensioners, and businessmen to meet eligible personal or professional financial needs. Instead of one standard personal loan, the bank uses borrower-specific schemes with different loan limits, repayment periods, and eligibility conditions. Interest rates are competitive and linked to the applicable benchmark and scheme. Eligible borrowers can also explore related options such as Festival Advance, salaried cash credit, Sahafat Finance, and other consumer-purpose loans.

J&K Bank Personal Loan Details
J&K Bank structures its personal financing according to the applicant category rather than offering one identical loan to every borrower. The loan amount, tenure, security, and charges therefore depend on the selected personal consumption loan scheme.
| Particular | J&K Bank Personal Loan |
| Official product category | Personal Consumption Loan |
| Interest rate | Competitive, scheme-based rates linked to the applicable benchmark |
| Applicant categories | Employees, professionals, pensioners/family pensioners, and businessmen |
| Loan amount | Depends on applicant category, income, and scheme |
| Maximum published tenure | Up to 10 years for eligible employee loans |
| Margin | Nil under the main Personal Consumption Loan schemes |
| Processing fee | Nil or applicable depending on the scheme |
| Repayment | Generally through monthly installments for term loan products |
| Digital options | Instant loans and other digital loan facilities are available for eligible customers/products. |
J&K Bank Personal Loan Interest Rate
J&K Bank does not currently present one universal headline percentage for every personal consumption loan. Pricing differs by borrower category and is linked to the bank’s applicable benchmark rate plus the spread assigned to the scheme.
The current Personal Consumption Loan structure uses the 3-year MCLR with a scheme-specific spread. Employees maintaining a salary account with J&K Bank and eligible pensioners have a lower spread than professionals, businessmen, or employees who do not maintain their salary account with the bank.
Since benchmark rates can change, it is more accurate to describe J&K Bank Personal Loan pricing as competitive and scheme-based rather than quoting one permanent interest rate for all borrowers. Applicants should check the applicable rate at the time of sanction.
What Can Affect the Applicable Personal Loan Rate?
The scheme selected is one of the main factors determining pricing. The applicant’s financial position and relationship with the bank can also affect the final sanctioned terms.
- Applicant category and personal consumption loan scheme
- Salary, pension, or business relationship with J&K Bank
- Applicable MCLR or other benchmark
- Income and repayment capacity
- Existing loan obligations
- Loan amount and repayment period
- Credit assessment and sanction terms
Ready to take the next step?
Types of J&K Bank Personal Loans
The bank offers separate personal consumption loan schemes for different borrower profiles. Choosing the relevant scheme is important because the loan limit, tenure, security requirements, and charges can vary considerably.
Personal Consumption Loan for Employees
This scheme is intended for eligible permanent employees of government bodies, PSUs, autonomous institutions, reputed institutions, and approved corporate houses. The loan can be used for personal needs.
- Minimum loan amount: ₹50,000
- Eligible government/PSU employees maintaining a salary account with J&K Bank: up to 42 times monthly gross salary
- Government employees without a J&K Bank salary account: up to 24 times monthly gross salary or ₹15 lakh, whichever is lower
- Eligible employees of reputed institutions/corporate houses with the required salary relationship: up to 30 times monthly gross salary or ₹25 lakh, whichever is lower
- Maximum repayment period: up to 120 months
- Margin: Nil
- Processing charges: Nil
Personal Consumption Loan for Professionals
This loan is designed for self-employed professionals such as doctors, engineers, architects, chartered accountants, and lawyers who maintain the required relationship with J&K Bank.
- Maximum finance: 2.5 times net annual income, 30 months’ net monthly income, or ₹20 lakh, whichever is lower
- Income is assessed using the average of the previous two years
- Maximum tenure: 7 years
- Margin: Nil
- Processing fee: 1% of the loan amount plus applicable GST, capped at ₹10,000 plus GST
Personal Consumption Loan for Pensioners
Central, State, and Union Territory government pensioners and eligible family pensioners maintaining a pension account with J&K Bank can access a separate personal consumption loan structure.
- Pensioners up to age 70: up to 30 times net monthly pension, subject to permissible deductions
- Pensioners above 70 and up to 74: up to 12 times net monthly pension
- Family pensioners up to age 70: up to 24 times net monthly pension or ₹3 lakh, whichever is lower
- Family pensioners above 70 and up to 74: up to 12 times net monthly pension or ₹2 lakh, whichever is lower
- Processing charges: Nil
- Margin: Nil
Personal Consumption Loan for Businessmen
This scheme serves existing businessmen who have the required banking relationship and satisfactory dealings with J&K Bank. The loan is intended for eligible personal needs.
- Finance: up to 30 months’ net monthly income
- Maximum loan amount: ₹20 lakh
- Income is derived from the average of the previous two years’ ITRs
- Maximum repayment period: 84 months
- Margin: Nil
- Processing fee: 1% of the loan amount plus applicable GST, capped at ₹10,000 plus GST
Not sure of your credit score? Check it now.
Other J&K Bank Personal Finance Schemes
Personal consumption loans are not the bank’s only options for individual borrowing. J&K Bank also lists several purpose-specific loans and credit facilities under its personal-loan and consumer-finance portfolio.
| Scheme | Main Purpose |
| Festival Advance Scheme | Short-term personal finance for eligible festival-related expenses |
| Cash Credit Scheme for Salaried Employees | Revolving credit for cyclic liquidity needs of eligible salaried employees |
| Sahafat Finance Scheme | Personal/professional finance for eligible journalists, media personnel, and media-house employees |
| Consumer Loan | Finance for household goods such as appliances, furniture, and electronics |
| Smartphone Finance | Finance for purchasing eligible smartphones |
| Coaching Fee Loan Scheme | Finance for coaching fees and selected related education expenses |
Festival Advance Scheme
The Festival Advance Scheme provides smaller personal loans for eligible employees and pensioners during specified festivals. It is separate from the standard personal consumption loan.
- Minimum finance: ₹5,000
- Maximum amount depends on salary or pension
- Repayment: 10 monthly installments
- Processing fee: Nil
- Prepayment penalty: Nil
Cash Credit Scheme for Salaried Employees
This facility is designed for eligible permanent employees drawing salary through J&K Bank who need revolving access to funds rather than a standard term loan.
- Minimum facility: ₹50,000
- Maximum: six times the average salary credited during the previous three months or ₹6 lakh, whichever is lower
- Processing charge: 0.25% of the amount plus GST, subject to the bank’s stated minimum and maximum
- No prepayment or foreclosure penalty
Sahafat Finance Scheme
Sahafat Finance combines term loan and cash credit facilities for eligible journalists, media personnel, and qualifying employees or owners of media organizations.
- Overall finance: up to 36 times net monthly income
- Minimum amount: ₹50,000
- Maximum amount: ₹3 lakh
- Term loan repayment: up to 60 monthly installments
- Processing charge: ₹200 plus GST
J&K Bank Personal Loan Amount and Tenure
There is no single maximum amount or tenure that applies to every J&K Bank personal loan. The limits depend on the borrower’s occupation, salary or pension, banking relationship, and selected scheme.
| Applicant Type | Loan Amount / Basis | Maximum Published Tenure |
| Eligible employees | Salary-multiple based; limits vary by employer and salary-account relationship | Up to 10 years |
| Professionals | Up to ₹20 lakh, subject to income-based limits | Up to 7 years |
| Businessmen | Up to ₹20 lakh, subject to income assessment | Up to 7 years |
| Pensioners | Based on multiples of net monthly pension | As per sanctioned repayment structure |
J&K Bank Personal Loan Eligibility
Eligibility differs substantially between schemes, so a single age or employment rule should not be applied to every applicant. J&K Bank primarily assesses occupation, income, banking relationship, and repayment capacity according to the chosen product.
Eligibility for Employees
Eligible applicants include permanent employees of Central, State, and Union Territory governments; PSUs; autonomous bodies; and approved institutions. Certain corporate-house employees can also qualify, subject to the required relationship with J&K Bank.
Government employees recruited under the specified SRO 202 framework in J&K and Ladakh require at least 18 months of service. Salary-account requirements differ by employee category.
Eligibility for Professionals
Doctors, engineers, architects, chartered accountants, lawyers, and other qualifying self-employed professionals can apply if they earn through their profession and maintain the required relationship with J&K Bank.
Eligibility for Pensioners
Eligible Central, State, and Union Territory government pensioners and family pensioners maintaining pension accounts with J&K Bank can apply. Co-applicant or guarantee requirements depend on the pension arrangement and availability of an eligible family pensioner.
Eligibility for Businessmen
An eligible businessman must generally have at least three years of satisfactory dealings with J&K Bank and maintain a current deposit account or business-loan relationship with the branch handling the loan.
Security and Guarantee Requirements
J&K Bank Personal Consumption Loans should not be described as universally unsecured. Security and guarantee requirements change according to the borrower and loan amount.
- Eligible government/PSU employees maintaining salary accounts with J&K Bank can receive the employee scheme without additional security.
- Other employee categories can require third-party guarantees.
- Professionals and businessmen can require guarantors, with additional collateral requirements for higher loan amounts.
- Pensioner loans can require an eligible spouse as co-applicant or other guarantees depending on the case.
Documents Required for J&K Bank Personal Loan
J&K Bank does not publish one universal document checklist across all current Personal Consumption Loan schemes. The documents required depend on the applicant category and the income or banking relationship used for assessment.
- Employees should be prepared to provide documents supporting employment, salary and the required salary-account relationship.
- Professionals need income information supporting the previous two years used for loan assessment.
- Businessmen are assessed using the previous two years’ ITR-based income and their existing banking relationship.
- Pensioners need records supporting their pension and pension-account relationship.
- KYC, application and any security or guarantor documents requested by the bank must also be completed.
Applicants should confirm the final checklist with J&K Bank for their chosen scheme instead of relying on a generic personal-loan document list.
Not sure of your credit score? Check it now.
J&K Bank Personal Loan Processing Fees
Processing charges are scheme-specific. Some borrower categories receive nil processing charges, while professional and businessman schemes carry an upfront fee.
| Personal Loan Scheme | Processing Charges |
| Personal Consumption Loan for Employees | Nil |
| Personal Consumption Loan for Pensioners | Nil |
| Personal Consumption Loan for Professionals | 1% of loan amount plus applicable GST, capped at ₹10,000 plus GST |
| Personal Consumption Loan for Businessmen | 1% of loan amount plus applicable GST, capped at ₹10,000 plus GST |
J&K Bank Personal Loan EMI Calculator
An EMI calculator can help estimate the monthly repayment before applying. Since J&K Bank uses scheme-specific and benchmark-linked pricing, the most useful calculation is based on the actual rate offered for the relevant product.
A longer tenure usually lowers the monthly EMI but increases the overall interest paid. A shorter tenure increases the monthly instalment while generally reducing the total interest cost.
Features of J&K Bank Personal Loan
The main advantage of J&K Bank’s personal-finance structure is that different schemes are designed for specific borrower groups instead of applying one set of terms to everyone.
- Separate Personal Consumption Loan options for employees, professionals, pensioners and businessmen
- Competitive scheme-based interest rates
- Employee repayment tenure of up to 10 years
- Loan amounts linked to income, salary or pension
- Nil margin under the main Personal Consumption Loan schemes
- Nil processing charges for eligible employee and pensioner loans
- Additional personal-finance options for festivals, salaried liquidity needs, consumer purchases and media professionals
- Digital and Instant Loan facilities available for eligible customers and products
Which J&K Bank Personal Loan Option Can You Consider?
The appropriate option depends mainly on who is borrowing and why the funds are required. The following comparison provides a simple starting point.
| Borrower / Requirement | Relevant J&K Bank Scheme |
| Permanent salaried employee | Personal Consumption Loan for Employees |
| Doctor, lawyer, CA, engineer or other eligible professional | Personal Consumption Loan for Professionals |
| Government pensioner or family pensioner | Personal Consumption Loan for Pensioners |
| Existing businessman with the required bank relationship | Personal Consumption Loan for Businessmen |
| Eligible festival-related short-term need | Festival Advance Scheme |
| Salaried employee needing revolving liquidity | Cash Credit Scheme for Salaried Employees |
| Journalist or eligible media professional | Sahafat Finance Scheme |
| Household appliances or furniture purchase | Consumer Loan |
How to Apply for J&K Bank Personal Loan
The application route depends on the selected scheme and whether the customer qualifies for a digital or instant-loan journey. Scheme-specific applications can also be completed through J&K Bank branches.
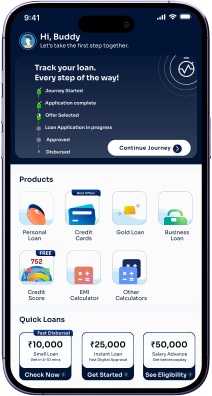
- Step 1: Visit buddyloan.com or download & install the Buddy Loan app (Android or iOS)
- Step 2: Open the personal loan application page. Provide the mobile number and enter the received OTP.
- Step 3: Specify the desired loan amount. Next, choose the Personal Loan option.
- Step 4: Choose the employment type (salaried or self-employed) and the salary mode (bank or cash).
- Step 5: Enter your work details (including company name, years of service and designation).
- Step 6: Enter your personal details (including full name, PAN, address, DOB & gender).
- Step 7: Provide your communication address and income details, and click the ‘Submit’ button.
Download the Buddy Loan App Now!
One solution to each of your financial needs at your fingertip.
Scan to download now