A laptop loan helps you finance a laptop without paying the full purchase price upfront. Depending on the lender and merchant, you can use a personal loan, consumer durable loan, EMI card, or another eligible financing option and repay the amount in installments. This can be useful for students, salaried professionals, self-employed users, and others who need a laptop for study, work, or personal use. Some eligible purchases also come with no-cost EMI or zero-down-payment offers.

Laptop Loan Interest Rate & Charges
The cost of a laptop loan depends on how you finance the purchase. A personal loan generally carries interest on the borrowed amount, while some consumer durable or merchant schemes can offer no-cost EMI on eligible laptops.
For example, IDFC FIRST Bank currently includes laptops under its Consumer Durable Loan and offers eligible laptop purchases from ₹5,000 to ₹8 lakh with repayment options of up to 24 months. No-cost EMI is available on qualifying products and schemes.
Bajaj Finance also provides laptop financing through its Insta EMI Card and partner-store financing. Eligible customers can choose repayment tenures from 3 to 60 months, while zero down payment is available on selected laptops.
Here is a list of top lenders and the proposed interest rates:
Top 10 Banks and NBFCs Offering Laptop Loans
| Lender | Interest Rate (p.a.) |
| HDFC Bank | 9.99% onwards |
| ICICI Bank | 9.99% onwards |
| Axis Bank | 9.99% onwards |
| IDFC FIRST Bank | 9.99% onwards |
| SBI | 10.05% onwards |
| IndusInd Bank | 10.49% onwards |
| Tata Capital | 10.99% onwards |
| Bajaj Finance | 0% on select laptop EMI offers; personal loans from 10% |
| L&T Finance | 10.50% onwards |
| Moneyview | 14% onwards |
If you use an unsecured personal loan instead, the lender will quote an interest rate based on your application. Before accepting any laptop loan, compare the annual percentage rate, processing fee, EMI, tenure, and total repayment rather than considering the advertised interest rate alone.
Laptop Loan Lenders
A laptop can be financed directly through a consumer durable scheme or indirectly through a personal loan that allows flexible use of the funds. Banks, NBFCs, and digital lending platforms therefore offer different ways to arrange a loan for a laptop purchase.
Top Banks and Loan Platforms to Buy a Laptop on EMI
The table below gives an updated view of selected personal-loan and digital-credit options. These are not all dedicated laptop loans, so the sanctioned funds can generally be used for a laptop purchase subject to the lender’s terms.
| Provider | Loan Amount |
| HDFC Bank | Up to ₹40 lakh |
| SBI Bank | Up to ₹35 lakh under the standard salaried personal loan proposition |
| Axis Bank | Up to ₹40 lakh |
| ICICI Bank | ₹50,000 to ₹50 lakh |
| MoneyTap | Up to ₹5 lakh |
| Buddy Loan | Depends on the lending partner and eligible offer |
| Loanbaba | Depends on the participating lender |
| PaySense | ₹5,000 to ₹5 lakh |
| Phocket | ₹5,000 to ₹2 lakh |
| Pocketly | ₹1,000 to ₹50,000 |
Note: Rates, loan amounts, APRs, and eligibility can change. Review the lender’s current offer and key fact statement before accepting a loan.
Laptop Loan Eligibility Criteria
There is no universal eligibility rule for every laptop loan. Requirements differ depending on whether you choose a personal loan, consumer durable loan, EMI card, or another financing facility.
Lenders commonly consider the following factors:
- Age: The applicant must fall within the lender’s permitted age range.
- Income: Regular and sufficient income can help demonstrate repayment capacity.
- Employment: Salaried, self-employed, and other eligible income profiles can qualify depending on the lender.
- Credit profile: Credit score and previous repayment behavior can affect eligibility, interest rate, and loan limit.
- Existing liabilities: Current EMIs and debts can influence how much additional finance a lender is willing to approve.
- Loan amount: Approval can also depend on the amount needed for the laptop and the applicant’s ability to repay it.
A higher credit score can improve the chances of receiving competitive terms, but there is no single score such as 750 that guarantees approval across all lenders.
Are you unsure about your credit score? You can check your credit score before applying and review your credit profile.
Calculate EMI for Your Laptop Purchase
Calculating the expected EMI can help you decide whether a laptop loan fits comfortably within your monthly budget. Use the loan amount, applicable interest rate, and repayment tenure to estimate the installment.
You can use an online EMI calculator to compare different loan amounts and repayment periods before applying.
| You can also estimate the EMI manually using the standard reducing-balance formula:
EMI = [P × R × (1+R)^N] / [(1+R)^N – 1] Where:
For example, assume you take a ₹1,00,000 laptop loan for 12 months at an illustrative interest rate of 12% p.a.
This calculation excludes processing fees and other charges. It is only an educational illustration and does not represent a current loan offer from a particular lender. |
A longer tenure can reduce the monthly EMI but usually increases the total interest paid. Compare both the monthly installment and overall repayment before choosing a tenure.
Documents Required For Online Laptop Loan
Document requirements depend on the lender and financing route. Pre-approved or consumer durable offers can involve a shorter process, while a fresh personal loan application can require additional KYC and income verification.
Commonly requested documents include:
- Identity Proof: Aadhaar Card, Passport, Voter ID, PAN Card, or Driving License, depending on the lender’s KYC process.
- Address Proof: Aadhaar Card, Passport, Driving License, utility bill, or another accepted address document.
- Income Proof: Salary slips, bank statements, income tax returns, or other income records where required.
- Employment or Business Proof: Employer details, employee ID, or business-related records depending on the applicant profile.
- Photograph: A recent photograph can be requested in some application journeys.
Digital lenders can also complete PAN, Aadhaar, OTP, or video-KYC verification online. Submitting documents does not guarantee approval because the lender still evaluates eligibility and repayment capacity.
Features & Benefits of Laptop Loan
A laptop loan can make a high-value laptop purchase easier to spread across a manageable repayment period. The actual benefits depend on whether you choose a personal loan, consumer durable finance, or an EMI-card facility.
- Lower upfront cost: Instead of paying the complete laptop price at once, you can spread the financed amount across installments.
- Multiple financing routes: Personal loans, consumer durable loans, and EMI cards provide different ways to fund the purchase.
- No credit card required in some cases: Consumer durable finance and EMI cards can provide alternatives to credit card EMI.
- No Cost EMI on eligible laptops: Some merchant or manufacturer-supported schemes offset the interest component.
- Zero down payment on selected products: Certain financing offers allow eligible buyers to finance the laptop without an upfront contribution.
- Flexible repayment: Tenure can vary from short consumer durable schemes to longer personal loan repayment periods.
- Online application: Many lenders allow KYC, eligibility checks, and loan applications through digital channels.
- No collateral for unsecured options: Personal and consumer durable loans generally do not require property or another asset as security.
Do not choose an option only because it offers the lowest EMI. A long tenure can make the monthly payment easier but can increase the overall borrowing cost.
Steps to Apply for Laptop Loan
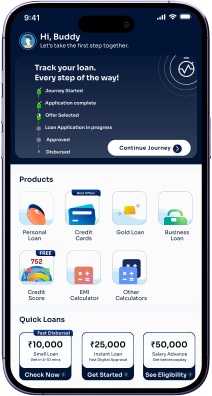
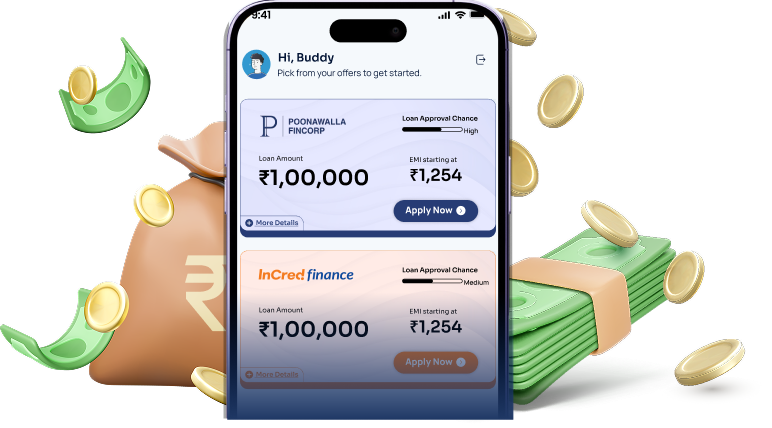
If you choose to fund the laptop through a personal loan, you can start an application through Buddy Loan and review eligible lender offers. The exact approval, loan amount, interest rate, and tenure will depend on the lending partner.
- Visit buddyloan.com or download and install the Buddy Loan app on Android or iOS.
- Open the Personal Loan Application Page and enter your mobile number to begin the application.
- Complete OTP verification and provide the requested loan amount and contact details.
- Select the employment or income profile available in the application journey.
- Enter the requested employment or business information.
- Provide personal and KYC details such as your name, PAN, date of birth, and address where requested.
- Add income and communication details and submit the application.
- Review the eligible lender offer, including the interest rate, APR, EMI, tenure, and applicable fees, before accepting the loan.
If you prefer a dedicated laptop financing option instead of a personal loan, you can also check eligible consumer durable or EMI-card offers available at the laptop retailer before making the purchase.
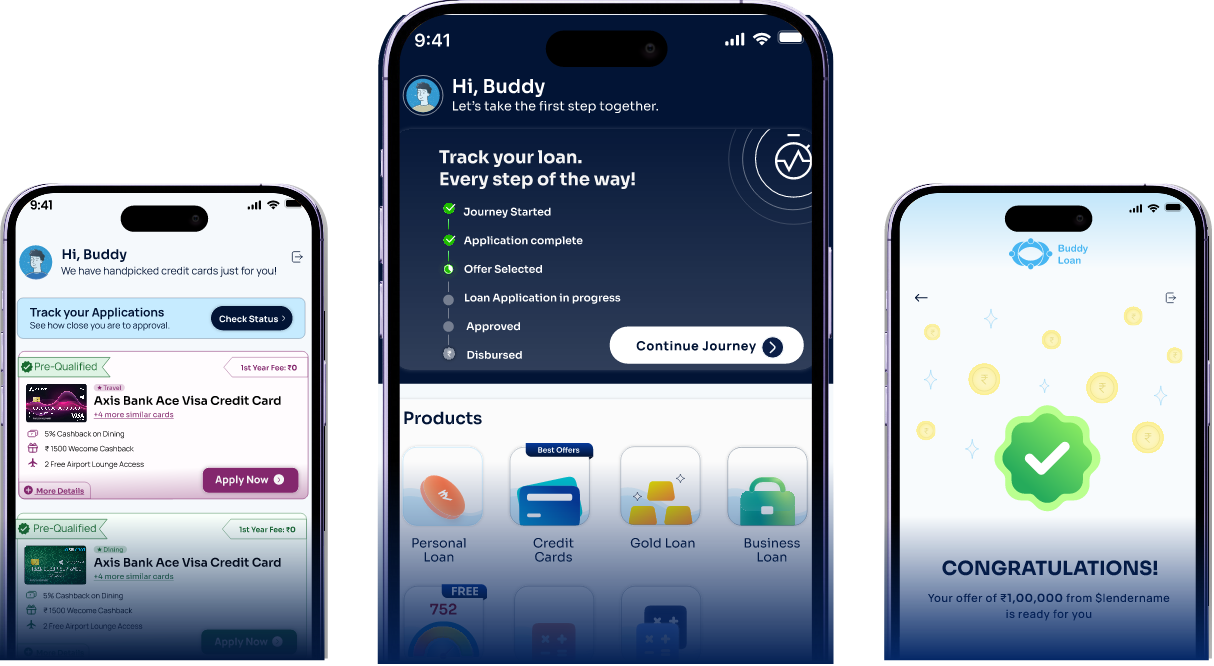
Download the Buddy Loan App Now!
One solution to each of your financial needs at your fingertip.
Scan to download now