Paying taxes is a civic duty, but there’s no harm in using legal strategies to reduce your tax liability. Most people are aware of common deductions such as Section 80C investments and home loan interest benefits. However, several lesser-known tax-saving options can help you optimize your income. In this article, we will uncover some hidden ways to save tax that many taxpayers overlook. From smart investment choices to employer-provided benefits and government incentives, these strategies can make a big difference in your overall tax planning.
1. Maximizing Section 80C Beyond the Usual Investments
Many taxpayers use Section 80C to claim deductions of up to ₹1.5 lakh, but they often stick to the usual options like PPF, ELSS, and fixed deposits. However, several hidden ways to save tax within Section 80C:
- Tuition Fees: Parents can claim tax deductions on tuition fees paid for up to two children.
- National Savings Certificate (NSC): Interest earned on NSC is reinvested and qualifies for deduction under Section 80C.
- Stamp Duty and Registration Fees: These costs associated with buying a home can be claimed under 80C.
By exploring these lesser-known options, you can fully utilize the ₹1.5 lakh limit.
2. Leveraging Section 80D for Health-Related Benefits
Medical expenses can be a significant burden, but the government offers tax deductions under Section 80D to ease this pressure:
- Preventive Health Check-ups: You can claim up to ₹5,000 for health check-ups for yourself and your family.
- Parents’ Health Insurance: Premiums paid for your parents’ health insurance (if they are senior citizens) can help you claim up to ₹50,000.
- Hindu Undivided Family (HUF) Benefits: If you belong to a Hindu Undivided Family (HUF), you can claim deductions for medical insurance under 80D.
3. Section 80E – Education Loan Interest Deduction
Higher education is expensive, but tax benefits can ease the financial burden. Under Section 80E, you can claim unlimited deductions on the interest paid on an education loan for yourself, your spouse, or your children.
The deduction is available for up to 8 years or until the interest is paid off, whichever is earlier. Unlike other sections, there is no upper limit on the amount of interest you can claim.
4. House Rent Allowance (HRA) Exemption for Rent Payers Without HRA
If your employer doesn’t provide House Rent Allowance (HRA), you can still use an HRA Calculator to determine your eligible deductions under Section 80GG.
Eligibility criteria:
- You should not be receiving HRA from your employer.
- You or your spouse should not own a residential property in the city where you reside.
- You must be living in a rented house.
The deduction is the least of the:
- ₹5,000 per month
- 25% of total income
- Actual rent paid minus 10% of income
5. Save Tax Through National Pension Scheme (NPS) Contributions
Many individuals overlook the additional tax benefits of NPS under Section 80CCD(1B). Apart from the ₹1.5 lakh limit under 80C, you can claim an additional ₹50,000 deduction on NPS contributions.
- Employers’ contributions to NPS (up to 10% of salary) are also exempt under Section 80CCD(2), providing further savings.
NPS not only secures your retirement but also helps you save significantly on taxes.
6. Leave Travel Allowance (LTA) for Domestic Travel
Many salaried employees forget to claim Leave Travel Allowance (LTA).
LTA can be claimed twice in a block of four years for travel within India. The exemption is available for travel expenses of the employee and their family but does not cover food, shopping, or hotel expenses.
7. Interest on Savings Accounts and Fixed Deposits
While interest earned on savings accounts is taxable, Section 80TTA allows a deduction of up to ₹10,000 per year on savings account interest.
For senior citizens, Section 80TTB provides a deduction of up to ₹50,000 on interest earned from fixed deposits, recurring deposits, and savings accounts.
8. Using Capital Gains Exemptions to Reduce Tax on Property Sales
If you’ve sold a property and made a capital gain, you can avoid paying tax by reinvesting it in specific instruments:
- Section 54: If you reinvest in another residential property within 2 years, you can claim an exemption.
- Section 54EC: Investing in specified capital gain bonds (like NHAI or REC) within 6 months can help you save tax.
These provisions can help significantly reduce or even eliminate capital gains tax.
9. Standard Deduction for Salaried Employees and Pensioners
Budget 2018 introduced a standard deduction of ₹50,000 for salaried employees and pensioners. Unlike other deductions, this is automatically available without requiring any investment.
For pensioners, this standard deduction helps reduce taxable pension income.
10. Home Loan Benefits – Principal, Interest, and Additional Deductions
Owning a house offers several tax-saving advantages:
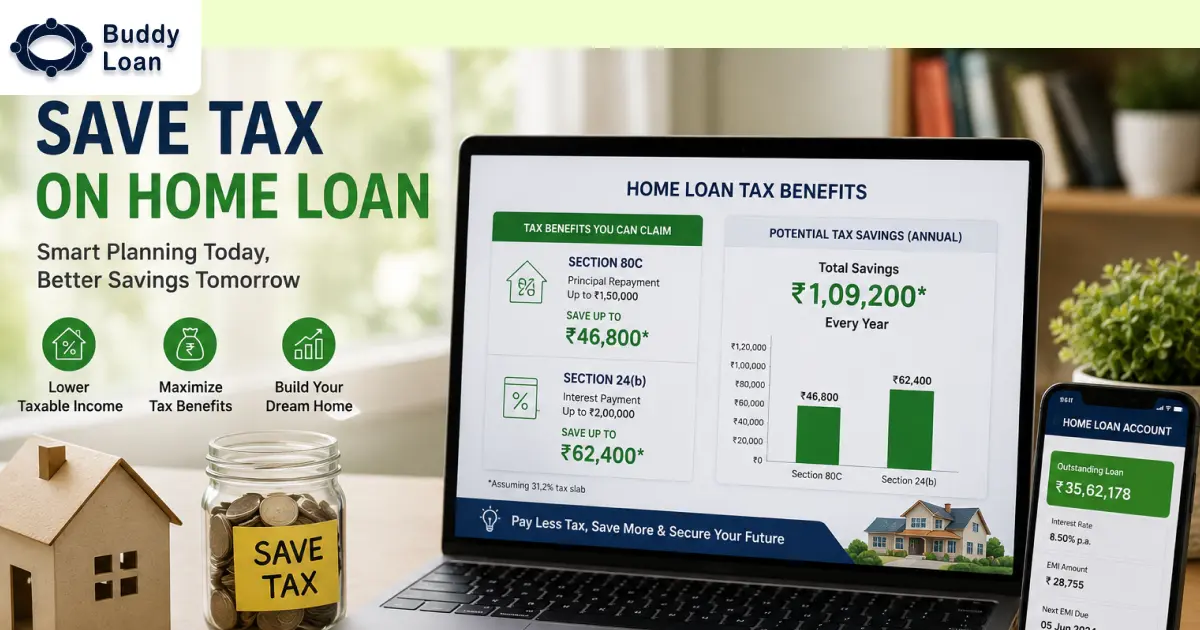
- Section 80C: Principal repayment up to ₹1.5 lakh is deductible.
- Section 24(b): Interest paid on home loans is eligible for deduction up to ₹2 lakh.
- Additional Deduction (Section 80EEA): First-time homebuyers can claim an extra deduction of ₹1.5 lakh on interest paid.
These deductions make homeownership a tax-efficient investment.
11. Donations and Charity Contributions (Section 80G)
Donating to recognized charitable organizations not only helps a cause but also reduces your tax burden.
Deductions range from 50% to 100% of the donation amount, depending on the institution.
- Donations to the Prime Minister’s Relief Fund or approved NGOs qualify for 100% deduction.
- Donations to other recognized charities qualify for 50% deduction.
12. Tax-Free Returns on Voluntary Provident Fund (VPF)
The Voluntary Provident Fund (VPF) is an extension of EPF, allowing employees to contribute up to 100% of their basic salary and DA. The contributions include:
- Tax deduction under 80C
- Tax-free interest (up to 9%)
- Tax-free withdrawals after 5 years
This is an excellent option for risk-free, tax-efficient savings.
Conclusion
Tax saving isn’t just about investing in PPFs and FDs. By taking advantage of these opportunities, hidden ways to save tax, you can legally reduce your tax liability while securing your financial future.
From leveraging employer-provided benefits and home loan deductions to maximizing NPS contributions and donations, these strategies can help you save thousands of rupees in taxes.
Start planning today and make the most of these smart tax-saving tricks!
Download the Buddy Loan App Now!
One solution to each of your financial needs at your fingertip.
Scan to download now