


Get a personal loan online at competitive interest rates. Choose flexible loan tenures that suit your repayment needs. With fast approval and quick disbursal, the loan amount can be credited directly to your bank account.
A personal loan can help you manage planned expenses, urgent payments, or short-term financial needs without pledging collateral. With Buddy Loan, you can check interest rates, fees, eligibility, documents, and repayment options. Compare offers from multiple lenders and choose a loan that fits your needs.
Apply for a personal loan online through a simple digital loan journey with flexible EMI options.
Personal Loan Details
A personal loan is an unsecured loan that can be used for multiple needs such as medical bills, home repairs, education costs, wedding expenses, travel, debt consolidation, emergency finance & more.
Since there is no collateral requirement, lenders usually review your income, repayment capacity, credit history, and existing obligations before showing an offer. Buddy Loan helps borrowers compare lenders through a digital lending process.
| Interest Rate | 9.99% p.a. onwards |
| Loan Amount | Starting from ₹10,000 to ₹35 lakhs |
| Tenure | Flexible loan tenures starting from 6 months to 5 years |
| Processing Fees | 0.5% to 4% of the loan amount (may vary across lenders) |
| Documentation | E – Documentation (PAN, Aadhaar, Income Proof) |
Note: Rates, charges, and amounts can vary by lender, customer profile, and internal credit assessment. Always review the lender offer before accepting it.
Personal Loan EMI Calculator
An EMI calculator is a tool that helps you determine your monthly payments towards your loan.
The Personal Loan EMI Calculator helps you estimate the monthly repayment amount before you apply. Enter the loan amount, interest rate, and tenure to see the EMI, total payable amount, and total interest.
For example, a longer tenure can reduce the monthly EMI but may increase total interest. A shorter tenure can increase the EMI but may reduce total interest. Use the calculator before submitting the application so you can make a practical borrowing decision.
Personal Loan Features & Benefits
Meet your financial needs with the easiest finance solution and cover all your expenses with an instant loan.
Quick Approval
Get your loan approved within minutes.
No Collateral
Get funds without risking your assets.
Low Interest Rates
Starting from 11.99% p.a.
Flexibility
Can be used for a variety of purposes.
Easy Repayment
Choose your preferred repayment tenure.
No Prepayment Penalties
No hidden charges or extra penalties.
Types of Personal Loans in India
Let’s go through the different types of personal loan options from below:
Instant Personal Loans
Get instant funds without collateral for urgent financial needs. Enjoy quick approvals, minimal documentation, and flexible usage, making it a reliable solution for emergencies anytime and anywhere.
Short-term Personal Loan
Access quick funds for immediate financial needs with short repayment tenures. Benefit from fast approvals, easy processing, and manageable EMIs, making it ideal for temporary cash flow gaps.
Travel Loan
Make your dream vacation a reality with easy travel financing. Cover flights, hotels, and other expenses with quick disbursal, allowing you to plan and enjoy stress-free trips.
Marriage Loan
Celebrate your special day without financial worries. Cover wedding expenses like venue, catering, and decor with flexible repayment options, ensuring your big day remains memorable and stress-free.
Medical Loan
Manage medical emergencies without financial stress. Get quick approvals to cover hospital bills, treatments, and procedures, ensuring timely care while allowing you to focus completely on recovery.
Student / Education Loan
Secure your academic future with ease. Cover tuition fees and education-related expenses with affordable repayment options, ensuring uninterrupted learning while reducing the financial burden on you and your family.
Consumer Durable Loans
Get easy financing without collateral for purchasing appliances and electronics. Enjoy quick approvals, minimal documentation, and flexible EMIs, making it a reliable solution for upgrading your lifestyle affordably.
Debt Consolidation Loan
Get a single loan without collateral to combine multiple debts into one. Enjoy lower interest rates, simplified repayments, and better control, making it a reliable solution to manage finances efficiently.
Also Read: Types of Personal Loans in India
Compare Best Personal Loan Offers
The best personal loan rates depend on your eligibility, income, credit score, employer category, location, and repayment history. Instead of choosing only by the lowest advertised rate, compare the processing fee, maximum amount, tenure, and total repayment cost.
Let’s go through some lender-wise loan options from below:


These offers are indicative values. Final offers are shown after lender-side checks and verification.
Your loan should match your income, EMI comfort, loan eligibility, digital application preference, fast loan disbursal need, and flexible EMI repayment plan. Review every loan offer carefully before accepting.
Why Choose Buddy Loan
Buddy Loan makes it easier to find the right loan by connecting you with verified lenders through one simple digital platform.
- Compare loan options from 30+ verified banks and NBFCs to choose the best option.
- Receive personalised offers based on your profile, income, credit score, location, and repayment capacity.
- Get personal loan options up to ₹35 lakhs.
- Apply online with a quick, 100% digital and paperless process.
- Interest rates start from 9.99% p.a. onwards.
- No need to apply separately with multiple lenders or worry about multiple credit checks.
- Check your eligibility and access your loan journey through the Buddy Loan website or app.
Note: Buddy Loan is a loan aggregator, not a direct lender. Final approval, interest rate, processing fee, loan amount, tenure, and disbursal timeline depend on the lending partner and applicant eligibility.
Personal Loan Interest Rates by Banks
Comparing bank-wise personal loan interest rates helps you shortlist lenders before applying for a loan. Public sector banks, private sector banks, foreign banks, and small finance banks may follow different pricing, approval, and documentation policies. Take time to explore and compare the different rates available to secure a better deal.
Personal Loan Interest Rates by Public Sector Banks
Public sector banks are often preferred by borrowers looking for transparent charges, stable service, and competitive rates. Approval may depend on income, employer profile, credit score, and internal bank policies.
| Bank Name | Interest Rate (p.a.) | Processing Fee | Max Loan Amount | Apply Online |
| Bank of Maharashtra | 8.75% onwards | Up to 1.00% | ₹20 lakh | Apply Now |
| Indian Bank | 9.00% onwards | Up to 1.00% | ₹50 lakh | Apply Now |
| Central Bank of India | 11.15% onwards | Up to 1.00% | ₹20 lakh | Apply Now |
| State Bank of India | 10.00% onwards | Up to 1.50% | ₹50 lakh | Apply Now |
| Bank of Baroda | 10.15% onwards | Up to 2.00% | ₹50 lakh | Apply Now |
| Punjab National Bank | 10.25% onwards | Up to 1.00% | ₹20 lakh | Apply Now |
| Punjab and Sind Bank | 9.70% onwards | Up to 1.00% | ₹20 lakh | Apply Now |
| Bank of India | 10.85% onwards | Up to 1.00% | ₹20 lakh | Apply Now |
| Indian Overseas Bank | 10.85% onwards | Up to 0.75% | ₹15 lakh | Apply Now |
| Canara Bank | 9.70% onwards | Up to 0.50% | ₹30 lakh | Apply Now |
| IDBI Bank | 10.50% onwards | Up to 1.00% | ₹25 lakh | Apply Now |
| Union Bank of India | 8.75% onwards | Up to 1.00% | ₹50 lakh | Apply Now |
| J&K Bank | 10.50% onwards | Up to 1.00% | ₹50 lakh | Apply Now |
| UCO Bank | 9.95% onwards | Up to 1.00% | ₹20 lakh | Apply Now |
Note: Final interest rates and processing fees vary based on individual credit scores (CIBIL), monthly income, and loan tenure as set by each respective lender’s Key Fact Statement (KFS). All processing fees listed are subject to 18% GST extra unless explicitly stated as inclusive by the lender.
Personal Loan Interest Rates by Private Sector Banks
Private sector banks often provide faster digital processing, higher loan amounts, and broader customer segments. These lenders may be useful when you want online loan approval with a smoother digital journey.
| Bank Name | Interest Rate (p.a.) | Processing Fee | Max Loan Amount | Apply Online |
| HDFC Bank | 9.99% onwards | Up to ₹6,500 | ₹50 lakh | Apply Now |
| ICICI Bank | 9.99% onwards | Up to 2.50% | ₹50 lakh | Apply Now |
| IDFC First Bank | 9.99% onwards | Up to 3.50% | ₹15 lakh | Apply Now |
| Bandhan Bank | 11.55% onwards | Up to 3.00% | ₹25 lakh | Apply Now |
| Axis Bank | 9.99% onwards | Up to 2.00% | ₹40 lakh | Apply Now |
| IndusInd Bank | 10.35% onwards | Up to 3.50% | ₹50 lakh | Apply Now |
| Yes Bank | 10.49% onwards | Up to 2.50% | ₹50 lakh | Apply Now |
| Kotak Mahindra Bank | 9.99% onwards | Up to 5.00% | ₹1 crore | Apply Now |
| City Union Bank | 11.50% onwards | Up to 1.00% | ₹10 lakh | Apply Now |
| Federal Bank | 12.00% onwards | Up to 2.00% | ₹25 lakh | Apply Now |
| Dhanlakshmi Bank | 11.90% onwards | Up to 2.00% | ₹15 lakh | Apply Now |
| South Indian Bank | 11.25% onwards | Up to 2.00% | ₹20 lakh | Apply Now |
| Karur Vysya Bank | 10.00% onwards | Up to 1.50% | ₹10 lakh | Apply Now |
| Karnataka Bank | 12.00% onwards | Up to 1.00% | ₹5 lakh | Apply Now |
| DCB Bank | 11.50% onwards | Up to 2.00% | ₹5 lakh | Apply Now |
| RBL Bank | 14.00% onwards | Up to 3.50% | ₹20 lakh | Apply Now |
| Tamilnad Mercantile Bank | 10.50% onwards | Up to 1.00% | ₹2 lakh | Apply Now |
Note: Final interest rates and processing fees vary based on individual credit scores (CIBIL), monthly income, and loan tenure as set by each respective lender’s Key Fact Statement (KFS). All processing fees listed are subject to 18% GST extra unless explicitly stated as inclusive by the lender.
Personal Loan Interest Rates by Foreign Banks
Foreign banks usually focus on salaried borrowers, premium customer segments, and clean credit profiles. Review the processing fee and eligibility requirements before applying.
| Bank Name | Interest Rate (p.a.) | Processing Fee | Max Loan Amount | Apply Online |
| HSBC Bank | 9.75% onwards | Up to 2.00% | ₹50 lakh | Apply Now |
| Citi Bank | 10.50% onwards | Up to 3.00% | ₹50 lakh | Apply Now |
| Standard Chartered Bank | 10.49% onwards | Up to 2.25% | ₹50 lakh | Apply Now |
Note: Final interest rates and processing fees vary based on individual credit scores (CIBIL), monthly income, and loan tenure as set by each respective lender’s Key Fact Statement (KFS). All processing fees listed are subject to 18% GST extra unless explicitly stated as inclusive by the lender.
Personal Loan Interest Rates by Small Finance Banks
Small finance banks can be useful for borrowers looking for accessible credit options across different income segments. Rates and charges may vary widely based on risk and borrower profile.
| Bank Name | Interest Rate (p.a.) | Processing Fee | Max Loan Amount | Apply Online |
| Ujjivan Small Finance Bank | 11.49% onwards | Up to 2.00% | ₹3 lakh | Apply Now |
| Jana Small Finance Bank | 15.00% onwards | Up to 3.00% | ₹15 lakh | Apply Now |
| AU Small Finance Bank | 11.00% onwards | Up to 3.00% | ₹10 lakh | Apply Now |
| Equitas Small Finance Bank | 12.00% onwards | Up to 2.50% | ₹15 lakh | Apply Now |
| Suryoday Small Finance Bank | 15.00% onwards | Up to 3.00% | ₹10 lakh | Apply Now |
| Unity Small Finance Bank | 14.00% onwards | Up to 2.50% | ₹5 lakh | Apply Now |
| ESAF Small Finance Bank | 13.50% onwards | Up to 2.00% | ₹10 lakh | Apply Now |
Note: Final interest rates and processing fees vary based on individual credit scores (CIBIL), monthly income, and loan tenure as set by each respective lender’s Key Fact Statement (KFS). All processing fees listed are subject to 18% GST extra unless explicitly stated as inclusive by the lender.
Personal Loan Interest Rates by NBFCs
NBFCs and digital platforms are often preferred for fast loan disbursal, simplified checks, and short-term borrowing options. They may be useful for borrowers who want quick cash funding, but the rate and fee can vary significantly. As always, it is best to compare the total cost before you select an offer.
| NBFCs | Interest Rates (p.a.) | Processing Fee | Max Loan Amount | Apply Online |
| Paysense | 14.00% onwards | Up to 3.00% | ₹15 Lakh | Apply Now |
| Cashe (Bhanix Finance) | 27.00% onwards | Up to 3.00% | ₹3 Lakh | Apply Now |
| Fibe | 12.00% onwards | Up to 3.00% | ₹10 Lakh | Apply Now |
| Incred | 11.49% onwards | Up to 3.00% | ₹15 Lakh | Apply Now |
| Mpokket | 22.00% onwards | Up to 3.75% | ₹50,000 | Apply Now |
| Prefr | 17.99% onwards | Up to 5.00% | ₹5 Lakh | Apply Now |
| NIRA | 24.00% onwards | Up to 5.00% | ₹1.5 Lakh | Apply Now |
| Money Tap | 13.00% onwards | Up to 2.50% | ₹5 Lakh | Apply Now |
| Bajaj Finance | 10.00% onwards | Up to 3.93% | ₹55 Lakhs | Apply Now |
| Tata Capital | 10.99% onwards | Up to 3.50% | ₹35 Lakh | Apply Now |
| Moneyview | 14.00% onwards | Up to 4.00% | ₹10 Lakh | Apply Now |
| Muthoot Finance | 13.50% onwards | Up to 3.00% | ₹20 Lakh | Apply Now |
| L&T | 11.00% onwards | Up to 3.00% | ₹15 Lakh | Apply Now |
| Upwards | 18.00% onwards | Up to 3.00% | ₹5 Lakh | Apply Now |
| Zype | 18.00% onwards | Up to 6.00% | ₹5 Lakh | Apply Now |
| HDB | 10.00% onwards | Up to 5.90% | ₹20 Lakh | Apply Now |
| LoanTaps | 15.00% onwards | Up to 2.00% | ₹10 Lakh | Apply Now |
| Phocket | 24.00% onwards | Up to 5.00% | ₹2 Lakh | Apply Now |
| Pocketly | 12.00% onwards | Up to 10.00% | ₹50,000 | Apply Now |
| Loanbaba | 11.00% onwards | Up to 2.50% | ₹1 crore | Apply Now |
| Dhani | 13.99% onwards | Up to 3.00% | ₹15 Lakh | Apply Now |
| Faircent | 12.00% onwards | Up to 8.00% | ₹10 Lakh | Apply Now |
| Finnable | 16.00% onwards | Up to 4.00% | ₹10 Lakh | Apply Now |
| Aditya Birla | 10.99% onwards | Up to 4.00% | ₹50 Lakh | Apply Now |
| MyMoneyMantra | 10.50% onwards | Up to 3.00% | ₹50 Lakh | Apply Now |
| IndiaLends | 10.25% onwards | Up to 4.00% | ₹70 Lakh | Apply Now |
| IIFL | 12.00% onwards | Up to 9.00% | ₹5 Lakh | Apply Now |
| Shriram Finance | 11.00% onwards | Up to 5.00% | ₹15 Lakh | Apply Now |
| Stashfin | 11.99% onwards | Up to 10.00% | ₹5 Lakh | Apply Now |
| Reliance | 12.00% onwards | Up to 2.50% | ₹15 Lakh | Apply Now |
| Piramal Finance | 12.14% onwards | Up to 5.00% | ₹10 Lakh | Apply Now |
| Rapid Rupee | 12.00% onwards | Up to 10.00% | ₹60,000 | Apply Now |
| Hero Fincorp | 11.00% onwards | Up to 3.00% | ₹5 Lakh | Apply Now |
| Flipkart | 12.50% onwards | Up to 2.00% | ₹2 Lakh | Apply Now |
| Paytm | 11.50% onwards | Up to 3.00% | ₹5 Lakh | Apply Now |
| Google Pay | 12.00% onwards | Up to 3.99% | ₹9 Lakh | Apply Now |
| PhonePe | 12.00% onwards | Up to 3.00% | ₹25 Lakh | Apply Now |
| Mobikwik | 12.00% onwards | Up to 3.00% | ₹5 Lakh | Apply Now |
| Rupee Redee | 24.00% onwards | Up to 10.00% | ₹1.5 Lakh | Apply Now |
| Olyv | 18.00% onwards | Up to 5.00% | ₹5 Lakh | Apply Now |
| Fatak Pay | 12.00% onwards | Up to 3.00% | ₹5 Lakh | Apply Now |
| Privo Loan | 13.49% onwards | Up to 3.00% | ₹5 Lakh | Apply Now |
| AXIO Loan | 14.00% onwards | Up to 3.00% | ₹4 lakhs. | Apply Now |
| Mahindra Finance | 8.00% onwards | Up to 2.00% | ₹15 Lakh | Apply Now |
| JIO Finance | 9.99% onwards | Up to 2.00% | Up to ₹1 crore | Apply Now |
| Credit Sea | 14.00% onwards | Up to 4.50% | ₹2 Lakh | Apply Now |
Note: Final interest rates and processing fees vary based on individual credit scores (CIBIL), monthly income, and loan tenure as set by each respective lender’s Key Fact Statement (KFS). All processing fees listed are subject to 18% GST extra unless explicitly stated as inclusive by the lender.
Personal Loan Eligibility Criteria
Loan eligibility is checked through basic personal, income, employment, and credit information. A higher income, stable job or business, good credit score, and low debt burden can improve approval chances.
Let’s go through the personal loan eligibility criteria for salaried and self-employed professionals from the table below:
| Eligibility Criteria | Salaried Individual | Self Employed |
| Age | 21 to 60 years old | 22 to 55 years old |
| Monthly income | ₹15,000 | ₹25,000 |
| Loan Amount | ₹50,000 to 25 lakhs | ₹50,000 to 50 lakhs |
| CIBIL Score | Above 750 | Above 750 |
Meeting the basic criteria does not guarantee approval. Lenders may also assess employer category, business vintage, salary mode, city, bank statement pattern, existing EMIs, and repayment behaviour.
How Credit Score Affects Your Personal Loan Application
Your credit score is one of the key factors lenders check before approving a your loan. Since a personal loan is usually an unsecured loan, lenders use your score to understand how responsibly you have handled past EMIs, credit cards, and other borrowings.
| Credit Score Range | What It Usually Means | Possible Impact on Personal Loan Application |
| 750 and above | Strong credit profile | Better approval chances, stronger offers, and possibly lower interest rates |
| 700 to 749 | Good credit profile | Approval is possible, but the final rate and loan amount may vary by lender. |
| 650 to 699 | Average credit profile | Lenders may do stricter checks and may offer a lower loan amount or higher rate. |
| Below 650 | Weak credit profile | Approval may be difficult, and lenders may ask for stronger income proof or a co-applicant. |
| No credit history | New-to-credit borrower | Approval may depend more on income, employment stability, bank statements, and lender policy. |
Minimum Credit Score Required for Personal Loan
There is no fixed minimum credit score required for every personal loan. Each bank and NBFC sets its own eligibility criteria, and your income, employment, existing EMIs and repayment history also influence approval.
| Credit Score | What It May Mean |
| 750+ | Generally viewed favourably by many lenders |
| 700–749 | May qualify with suitable income and profile |
| 650–699 | Loan options may be more limited |
| Below 650 | Approval can be more difficult |
A lower score does not automatically mean rejection. Lenders may assess your overall profile before deciding the loan amount, interest rate and tenure. Buddy Loan connects you with 30+ verified lenders, helping you compare suitable personal loan options based on your eligibility.
Documents Required to Apply for a Personal Loan
The documents required for a personal loan can vary depending on the lender, applicant type, loan amount, and verification process. Since most lenders now support a digital personal loan application, keeping your KYC, income proof, and bank statements ready can help make the process smoother. Here’s a list of documents required for a your loan.
Salaried applicants usually need to submit documents that verify their identity, address, employment, and monthly income.
Documents required:
- PAN card & Aadhaar card
- Address proof (Aadhaar card, passport, utility bill, or rental agreement)
- Latest salary slips, generally for the last 3 months
- Employee ID card or employment proof
In certain cases, alternative documents such as Form 16, Passport, voter ID, or driving licence, if required, can be used as additional identity proof. Same goes for bank statements, generally for the last 3 to 6 months, in dire cases where the salary slips are absent.
Location-Wise Personal Loan
Loan offers may vary by city because lenders consider location, income range, employer presence, and serviceability. You can check city-specific options to compare offers available for your profile.
A thorough selection of personal loan choices is available on our website, organised by your city & location. This makes evaluating many offers and selecting the best one simpler.
Additionally, you have the option to apply for a loan hassle-free online through our website.
Tips to Avoid Personal Loan Rejection
Rejection can happen due to low credit score, insufficient income, high existing EMIs, incorrect details, unstable employment, or incomplete documents. Here are some tips to improve your chances of getting a loan:
Maintain a good credit score
Pay EMIs and credit card bills on time. A score above 750 can improve your chances of getting better offers.
Check your credit report
If your credit score is low, review your credit report for errors. If you find incorrect details, raise a dispute with the credit bureau.
Keep your debt under control
Lenders check your income and existing EMIs before approving a loan. Try to reduce unpaid dues before applying.
Improve your income profile
A stable income makes repayment easier. Additional income sources may help if they can be properly documented.
Apply for the right loan amount
Borrow only what you need. Asking for a very high amount can reduce approval chances.
Choose the right lender
Apply with lenders whose eligibility criteria match your income, credit score, and employment type.
Avoid too many applications
Multiple loan applications can lead to repeated credit checks, which may slightly affect your credit score.
Keep documents ready
Missing or incorrect documents can delay approval or lead to rejection.
Add a co-applicant or guarantor if needed
If your profile is weak, a guarantor with a strong credit score and stable income may improve approval chances. However, the guarantor becomes responsible if you fail to repay.
Enter correct details
Make sure your PAN, Aadhaar, income, address, employment, and bank details are accurate.
Overall, maintaining a good credit score, a stable employment history, choosing the right lender, providing accurate information, and keeping your debt-to-income ratio low can improve your chances of getting a personal loan.
Steps to Apply for a Personal Loan with Buddy Loan
Here’s the step-by-step process that you can follow to apply for a personal loan on Buddy Loan:
Visit buddyloan.com or Download & install the Buddy Loan app (Android or iOS).
Open the Personal Loan Application Page. Provide the mobile number and enter the received OTP.
Specify the desired loan amount & personal email. Next, choose the Personal Loan option.
Choose the employment type (Salaried, Self-Employed, or Student) and the salary mode (bank or cash).
Enter your work details (Including company name, years of service and Designation).
Enter your personal details (Including Full Name, PAN, address DOB & Gender).
Provide your communication address, and income details and Click the 'Submit' button.
As per the details provided, suitable lenders will be allocated, and their respective details will be shared for future proceedings.
Personal Loan Prepayment & Foreclosure
Personal loan prepayment means paying part of your loan early, while foreclosure means closing the full loan before the tenure ends.
As per RBI’s latest guidelines, no pre-payment or foreclosure charges apply to loans sanctioned or renewed on or after January 1, 2026. Under these directions, lenders cannot charge prepayment or foreclosure fees on eligible floating-rate loans to individual borrowers. RBI had also earlier barred banks from charging such penalties on floating-rate term loans to individuals.
For fixed-rate personal loans, charges may still apply as per the lender’s policy and loan agreement. Before paying early, check your rate type, lock-in period, outstanding balance, prepayment fee, GST, and closure process. Always collect a no-dues certificate after full repayment.
Personal Loan Repayment
Repayment for a personal loan is usually done through fixed monthly EMIs. Choose a tenure that keeps the EMI affordable without increasing the total interest unnecessarily. Timely repayment for personal loans can protect your credit score and improve future loan eligibility.
Common repayment modes include:
- Auto-debit or NACH: EMI is deducted from your bank account on the due date.
- Online banking: Repay through the lender website, app, or net banking.
- UPI or payment gateway: Some lenders may allow digital repayment options.
- Branch payment: Some lenders may support in-person payment at selected branches.
Before accepting the offer, check due date, bounce charges, late payment fee, foreclosure terms, part-payment rules, and customer support process.
How to Access Your Personal Loan Statement Online
A personal loan statement helps you track your loan account, EMI payments, outstanding balance, interest charged, due dates, and repayment history. Most lenders allow borrowers to download it online through their website or mobile app.
Here is a step by step guide to show how you can access it:
- Visit the lender’s official website or mobile app.
- Log in using your registered mobile number, customer ID, loan account number, or email ID.
- Complete OTP or password verification.
- Go to the loan account, service request, or statement section.
- Select your personal loan account.
- Choose the statement period, if required.
- Download the loan statement in PDF format or request it by email.
Even if you applied through Buddy Loan, remember that Buddy Loan is a loan aggregator. The loan statement is usually issued by the final lending partner that approved and disbursed your loan. You can access the statement from that lender’s official app, website, customer portal, or customer support channel.
People Also Ask
Let’s go through some common personal loan queries which people may ask for:
- Which bank will give a personal loan easily?
There is no single bank that approves everyone easily. The loan approval depnds on your creditworthiness and the lender’s policies. Buddy Loan helps you compare options from 30+ verified lenders, including banks and NBFCs, based on your profile. - How to get 40,000 rupees urgently?
You can compare various verified lenders and apply online for a ₹40,000 personal loan through Buddy Loan. Ability to compare and choose your loan offers can help you with better chances of loan approval. Complete the digital application and check eligible offers from multiple lenders in one place. - Can I get a ₹20,000 loan without income proof?
It depends on the lender. Some may accept alternative documents such as bank statements or other income details instead of a salary slip. Comparing these lender options can be a effective way and Buddy Loan helps you do that. - How can I get a personal loan immediately?
Apply online and keep your KYC and required financial details ready. Digital processing can be faster, but approval and disbursal are subject to lender verification and eligibility. - Can I get a 5 lakh loan for a 20,000 salary?
It is possible with some lenders but not guaranteed. A lender may consider your ₹20,000 income, credit score, existing EMIs, employment and repayment capacity before deciding the eligible amount. - Can I get a personal loan quickly?
Yes, online personal loans can be processed quickly when you meet the lender’s criteria and have the required documents ready. Buddy Loan helps you compare 30+ verified lenders through one digital platform. - Can I get a ₹50,000 personal loan without a salary slip?
Possibly. Some lenders accept alternative income documents or bank statements, depending on your employment profile. The required documents vary by lender. - Is 700 a bad CIBIL score for personal loan?
A 700 credit score is not necessarily bad. It depends on your creditworthiness and lender’s eligibility criteria. - Can I get a loan if I’m unemployed?
A personal loan can be difficult without regular income because lenders assess repayment capacity. You may still qualify if you have another verifiable source of income, subject to lender criteria. - Which loan app is safe?
Choose an app that clearly identifies its lending bank or NBFC and is associated with an RBI-regulated entity. RBI recommends verifying this association and avoiding loan apps received through SMS or social-media links. Buddy Loan connects borrowers with 30+ verified lenders. - How to successfully get a personal loan?
Check your eligibility, choose an affordable loan amount, maintain a healthy credit score and submit accurate documents. Buddy Loan offers personal loan options up to ₹35 lakhs, with interest rates starting from 9.99% p.a. onwards, subject to lender eligibility. - Can I get a loan with no income verification?
Usually, no. Lenders need to assess your repayment capacity, so they may verify income through salary slips, bank statements, tax records or other financial documents. Requirements vary by lender. - Can I get a ₹3 lakh loan without a credit score?
It can be difficult, but some lenders may consider applicants with limited or no credit history using other factors. Approval depends on income, repayment capacity and the lender’s criteria. Buddy Loan helps you compare options from 30+ verified lenders. - How much EMI for a ₹7 lakh loan?
Your EMI depends on the interest rate and tenure. For example, a ₹7 lakh loan for 5 years would have an EMI of about ₹14,869 at 9.99% p.a. and ₹16,288 at 14% p.a. Actual EMI varies by lender and offer. - Can a 650 credit score get a loan?
Yes, a 650 credit score does not automatically mean rejection, but loan options may be more limited and the interest rate may be higher. Lenders also consider income, existing debt and repayment history.
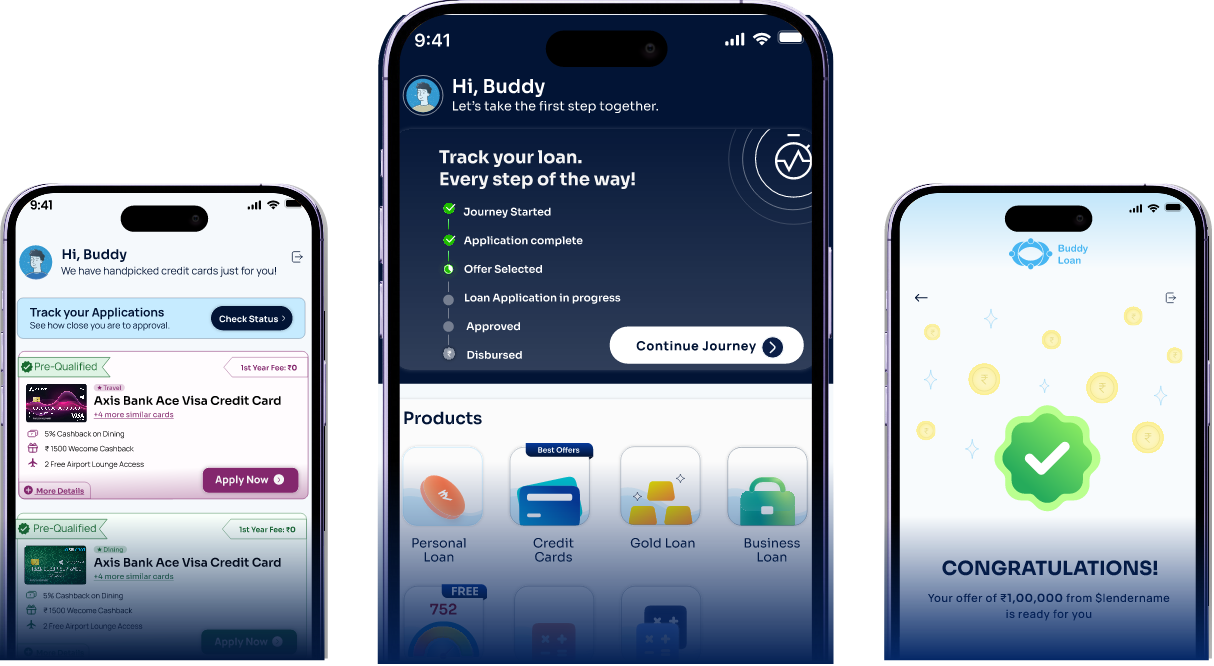
Download the Buddy Loan App Now!
One solution to each of your financial needs at your fingertip.
Scan to download now


Customer Stories
Over 500K+ 5-star reviews


“The app experience was smooth and easy to understand.”

Rahul Mehta
Bengaluru
